

03/25/2026
Hong Kong Company Annual Compliance: Requirements & Process
Introduction
Incorporating a Hong Kong private limited company can take only two days but maintaining it requires strict adherence to annual filing with the Companies Registry schedules. In this article, we look to clarify the main points of Hong Kong company annual compliance requirements in Hong Kong and how you can prepare in advance to present the filings and maintain good standing with Hong Kong authorities.
In Hong Kong, companies must comply with two main Hong Kong authorities:
- The Hong Kong Companies Registry (CR), where the company must present information related to corporate governance & ownership records, including changes of shareholding, directors, address, etc.
- And the Inland Revenue Department (IRD), to whom the company will present taxation information and the renewal of the business registration.
It is imperative that your private limited company follow the deadlines and the corresponding filings strictly; the cost of inaction for a company can result in financial penalties, court summonses, and even the company strike-off.
The Annual Compliance Requirements (At a Glance)
Our experts prepared a high-level summary table where you can consult, in an easy and practical way, the compliance in Hong Kong, including the core filing obligations, authorities to present, and the deadlines that Hong Kong companies must adhere to.
| Statutory Requirements | Authority | Filing Document | Standard Deadline | Mandatory Fee (2026) |
| Annual Return | Hong Kong Companies Registry (CR) | Form NAR1 | Within 42 days of incorporation anniversary | HK$105 |
| Business Registration Renewal | Inland Revenue Department (IRD) | BR Certificate Renewal | 1 month before expiry (1-year or 3-year certificate) | HK$2,350 (1-year) |
| Profits Tax Return (PTR) | Inland Revenue Department (IRD) | PTR + Audited Accounts | 1 month from issuance (or Block Extension date) | Varies by tax liability |
| Employer’s Return | Inland Revenue Department (IRD) | Form BIR56A & IR56B | Issued early April; due within 1 month | Nil (reporting only) |
| Significant Controllers Register (SCR) | CR / Internal | Physical/Digital SCR | Maintained continuously at registered office | Nil |
| Annual General Meeting | Nil | Annual General Meeting minute | Annual completion | Nil |
Core Pillar Breakdown – The Essential Annual Filings Requirements in Hong Kong
To provide more detail regarding each one of the filings and Hong Kong's annual compliance, here is further information for you to understand the purpose of each requirement and what are the steps a company in Hong Kong must follow to be compliant.
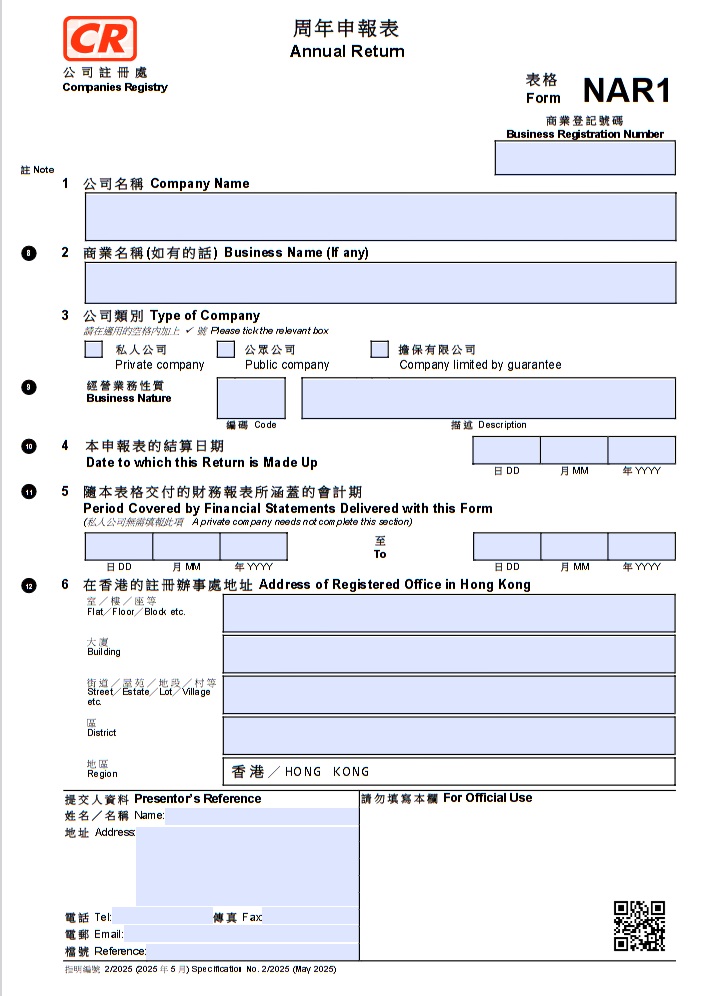
1. Annual Return (Form NAR1) to Hong Kong Companies Registry
- Purpose: Under section 662 of the Companies Ordinance (Cap. 622), all private limited companies must deliver to the Registrar for registration an annual return. The purpose of the Annual Return is to provide an update of statutory records regarding the company directors, shareholders, company secretary, and registered office address. This information is filed with the Companies Registry. The information of companies registered in Hong Kong will be public via the Companies Registry e’Services portal.
- The Rule: Companies shall file an Annual Return every calendar year (except the year of incorporation) within 42 days of the company's incorporation anniversary date. For clients, Element 8 Consulting will remind them two months in advance of the anniversary date to avoid any penalties. Ig you are using another service provider, we advise setting a calendar reminder for your company and filing on time. Companies will perform the filing with the help of their Company Secretary; companies in Hong Kong must appoint a Hong Kong resident or a licensed TCSP company to serve as such.
- Crucial Myth: Some directors believe that if there are no changes in the company details during the year, it is not necessary to file the Annual Return. This is false; even if there are no changes, presenting the Annual Return form remains legally mandatory.
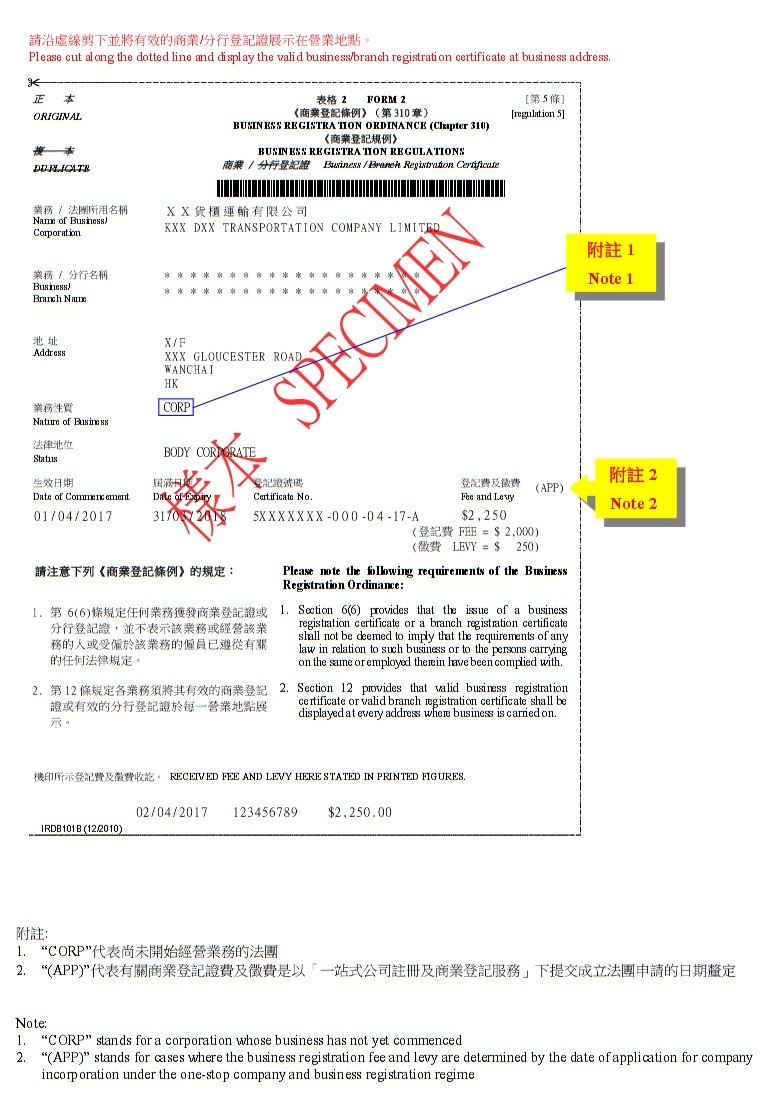
2. Business Registration Certificate (BRC) Renewal
- Purpose: Applying for the renewal of the Business Registration Certificate renews the company’s legal business operating license and tax identification number with the Inland Revenue Department (IRD).
- The Rule: Managed via the IRD’s Business Registration Office. The notice for renewal is typically sent one month prior to the expiry date, which is on the anniversary date of the company. Similar to our reminder of the Annual Return. Element 8 Consulting notifies clients two months prior to the anniversary of the company.
3. Statutory Audit & Profits Tax Return (PTR) Submission
- Purpose: The purpose of preparing the audit and the Profit Tax Return (PTR) or tax filing is to report the company's earnings during the last fiscal year and determine the corporate tax liability. The company should adhere to Hong Kong accounting standards and maintain proper accounting records and annual accounts to file on time.
- The Supporting Documents: It is important to note that the PTR cannot be submitted alone; the company must submit it together with their Audited Financial Statements signed by an independent Hong Kong Practicing Certified Public Accountant, together with a formal tax computation.
Once the company is established, the first PTR will arrive within 18 months of the incorporation of the entity, and new entrepreneurs will have three months to file the PTR with the authority. Thanks to the great flexibility and pro-business law, the company can select the fiscal year-end. The first fiscal year can include less than twelve months or more but not exceed eighteen months.
In the following years, the PTR will arrive after the end of the fiscal year, usually every April. Depending on the year-end, the company must present its declaration on a specific date. The dates for each specific year will be published on the Government's official website.
N Code:
- Accounting Period: For companies with an accounting period from 1 April to 30 November
- Due date: 4 June
- Electronic Filing Extension: Not available
D Code:
- Accounting Period: For companies with an accounting period from 1 to 31 December
- Due date: 31 August
- Electronic Filing Extension: 2 October
M Code:
- Accounting Period: For companies with an accounting period from 1 January to 31 March
- Due date: 16 November
- Electronic Filing Extension: 16 December
4. Employer’s Return of Remuneration (BIR56A / IR56B)
- Purpose: The Employer’s Return (ER) serves the purpose of reporting salaries, bonuses, and pensions paid to Hong Kong residents or overseas staff and directors during the tax year.
- Sole Director Rule: Must be filed even if the only paid individual is the director or filed as "NIL" if there are no employees.
- The Rule: The Employer’s Return is filed with the Inland Revenue Department. The ER must include the period from 1 April to 31 March of the next year. The company will receive at its registered address the corresponding notice to be completed and filed.
5. Annual General Meeting
- Purpose: Under the Hong Kong Companies Ordinance (Cap. 622), an Annual General Meeting serves as the primary forum for shareholders to review company performance, lay audited financial statements, and decide on critical governance matters.
- The Rule: Unlike prior regulations tied strictly to calendar years, for Cap. 622, Annual General Meeting companies must pay attention to its annual Accounting Reference Period (ARP):
Private Companies (Not part of a public group): Must hold an Annual General Meeting within 9 months after the financial year-end.
Public Companies / Listed Entities: Must hold an Annual General Meeting within 6 months after the financial year-end.
First AGM Exception: For new entities with an initial financial year exceeding 12 months, the deadline is the later of 9 months after the first anniversary of incorporation or 3 months after the financial year-end.
The Annual Compliance Execution Path
As a general guide, you can consult the following steps to consider the order of each filing.
1. Maintain Statutory Registers & Bookkeeping: Ongoing.
Keep accounting records up to date monthly and maintain internal records (Significant Controllers Register, Member Register, Director Register) at the registered office.
2. Renew Business Registration Certificate: 1 Month Before BR Expiry.
Pay the annual BR levy to the IRD Business Registration Office and display the updated certificate at your principal place of business.
3. Submit Annual Return (Form NAR1): Within 42 Days of the incorporation date.
Private limited companies in Hong Kong are required to file the Annual Return via the Companies Registry e-Services Portal or through your appointed Company Secretary, along with the HK$105 government fee.
4. Complete Employer's Return: Early April Every Year.
Submit the Employer's Return BIR56A/IR56B within 30 days. The filing must include salaries for employees and directors, if applicable.
5. Annual Audit and PTR filing: Depending on the accounting year-end. Finalise the financial accounts with your auditor in preparation for the Profits Tax Return (PTR). File before the due date to avoid penalties and court summons.
Late Filing Penalties & Escalating Fines
As mentioned previously, if the company files any compliance return late, it is subject to specific penalties.
Escalating NAR1 Late Filing Fees (Companies Registry)
- Within 42 days: If the company files within this period, it will pay the standard fee of HK$105.
- 42 days to 3 months late: After this period, the company will pay a penalty of HK$870.
- 3 to 6 months late: The corresponding penalty is HK$1,740.
- 6 to 9 months late: The amount goes to HK$2,610.
- Over 9 months late: The higher penalty before court summons is HK$3,480.
Legal Risk: Directors face maximum fines of up to HK$50,000 per breach, plus daily default fines for continued non-compliance, and potential court prosecution or company deregistration.
Conclusion
Hong Kong compliance obligations are simple, predictable, and fair—but it requires proactive tracking to prevent costly administrative fees.
If you require assistance with your annual compliance obligations, our experts at Element 8 Consulting can help you to set a calendar of due dates and a specific plan together with your team to maintain proper records, file documents on time, and avoid any penalties. Get in touch with us at info@element8.hk and learn more about how we can bring our individualised touch to your company’s administration.
Book a Free 15-Minute Compliance Review
Frequently Asked Questions
What happens if I miss the 42-day Annual Return (Form NAR1) deadline?
If you happen to file the Annual Return late, your Hong Kong private limited company must pay a specific penalty depending on the number of days overdue from the anniversary date of the company. At Element 8 Consulting, we support our clients with a timely reminder of all their compliance due dates.
- Within 42 days: Hong Kong companies must file an annual return within this period. If the company files within 42 days, it will pay the standard fee of HK$105.
- 42 days to 3 months late: Pay a penalty of HK$870.
- 3 to 6 months late: The corresponding penalty is HK$1,740.
- 6 to 9 months late: The amount is HK$2,610.
- Over 9 months late: The higher penalty before court summons is HK$3,480.
Does my company still need an audit and tax return if it had zero business activity this year?
Yes, all Hong Kong-registered companies, even inactive companies, must submit Profits Tax Returns (often as a "Nil" return) and maintain valid Business Registration Certificates. If your company has been inactive for a while and you have not taken any action with your annual accounts and tax filing, get in touch with Element 8 Consulting at info@element8.hk.
Can I get an extension on my Profits Tax Return submission?
Yes, but usually only if you file through an authorised Tax Representative under the IRD Block Extension Scheme. IRD deadlines can be tight, and filing a PTR is a legal requirement for all Hong Kong private limited companies. If your company needs to apply for Block Extension Schemes, Element 8 Consulting can support you in extending the Tax Return submission.
How far in advance should I prepare my accounts before the HK audit deadline?
Business owners often do not realise that audited financial statements must accompany the Profits Tax Return. At Element 8 Consulting, we advise our clients to start 2–3 months early, avoiding last-minute scrambling and late filing.